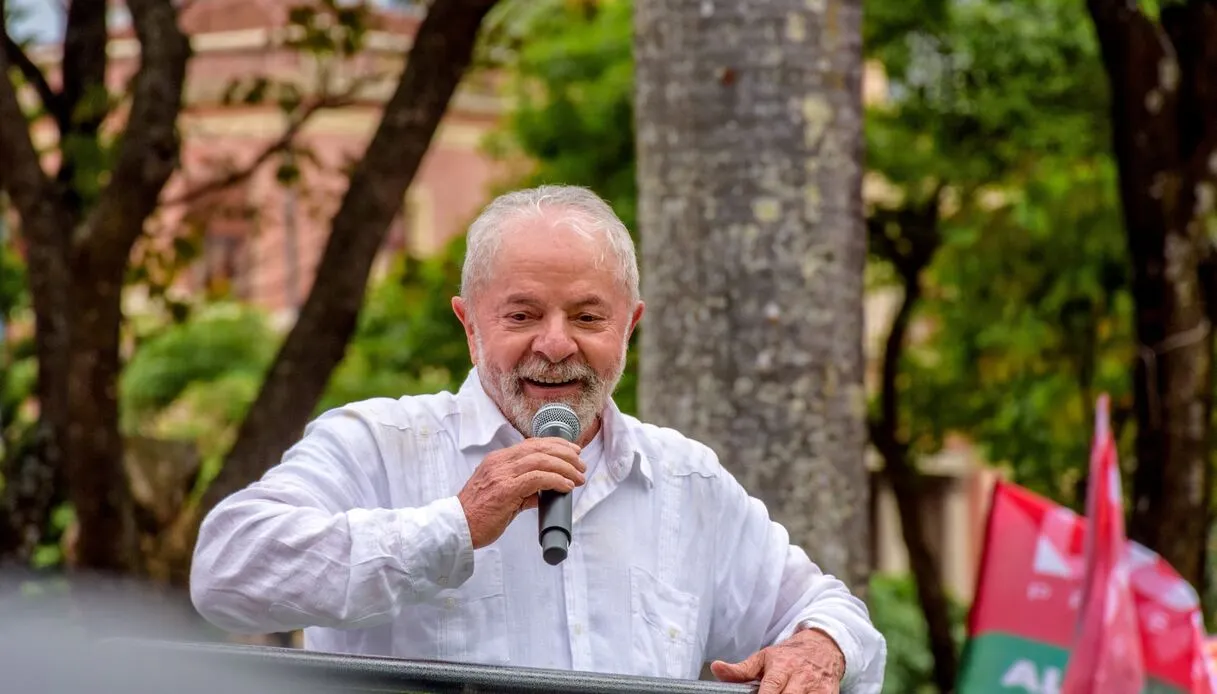
The electoral victory arrived on Sunday, the financial account the following day. In Brazil, the re-election of Luiz Inácio Lula da Silva provoked a violent reaction from the markets: the São Paulo stock exchange lost almost 14% and the real suffered one of the worst devaluations in recent decades.
Behind these numbers there is not only the disappointment of investors who had bet on a change of government. There is a deeper question: how to finance public spending, support growth and contain debt without suffocating families and businesses with high interest rates?
It is the economic challenge of Lula’s fourth mandate, but also the reason why the result of the Brazilian elections affects those who invest in emerging markets and European companies operating in South America.
Brazil elections 2026, why Lula’s victory surprised the markets
The ballot on October 25 gave Lula 51.79% of the votes, against 48.21% for Flávio Bolsonaro, son of former president Jair. The result was confirmed by the Brazilian Superior Electoral Tribunal.
The surprise comes from the first round, when Bolsonaro preceded Lula, fueling expectations in the markets of policies more favorable to containing spending. The debate had also opened on the consequences of a possible Bolsonaro victory on the agreement between the European Union and Mercosur.
Investors had been buying Brazilian stocks and reals anticipating that scenario. Lula’s victory forced them to quickly review their positions.
The collapse does not necessarily represent a definitive failure of the Brazilian economy: it also reflects the dismantling of the financial bets built in the previous weeks.
Brazilian stock market falls, the real loses more than 8%
The session on Monday 26 October was particularly turbulent.
The Ibovespa index, the main reference of the Brazilian stock exchange of Sao Paulo (B3), which measures the performance of the most representative and liquid shares on the market, closed down by 13.9%, after trading had been temporarily suspended upon reaching the loss threshold of 10%.
The real lost around 8.1% against the dollar, with the exchange rate reaching around 5.415 reals per dollar. During trading it had also exceeded 5.60.
The sales also affected Brazilian government bonds, especially long-term ones.
The reaction also involved the Brazilian Treasury, which canceled the ordinary auctions of inflation-indexed and fixed-rate securities scheduled for 27 and 29 October.
Public debt and rates: Brazil’s real problem
To understand investors’ concerns we need to look at public finances.
According to analysis by JP Morgan Private Bank, Brazil’s gross public debt had reached 82.9% of GDP in August.
The Brazilian central bank also maintains the Selic rate, the country’s main reference interest rate, used to guide the cost of money and control inflation, at 13.75% per year: a high level, which makes it particularly onerous to finance investments and consumption.
Lula intends to preserve social programs and support domestic demand. The problem is reconciling these objectives with the need to stabilize the debt.
If investors perceive greater risk, they demand higher yields to buy Brazilian bonds.
The higher the interest on the debt, the greater the public resources needed to pay it. This reduces the space available for infrastructure, education and services.
Who loses and who stands to gain from the devaluation of the real
The devaluation of the Brazilian real does not produce the same effects on the entire economy. For some companies it can represent a competitive advantage, while for others it translates into higher costs and lower profit margins.
Families risk paying more for imported products, with possible repercussions on inflation. The situation is particularly delicate for companies indebted in foreign currencies: if the real loses value, more reais are needed to repay the same debt in dollars, unless there are adequate currency hedges.
On the contrary, exporters can benefit from a more favorable exchange rate, especially when they collect in dollars and bear part of the costs in local currency.
For those investing from Italy, currency risk deserves particular attention. A Brazilian stock can keep its price unchanged in real and still generate a loss when the capital is converted back into euros.
It is a risk that also concerns those who invest through index funds. QuiFinanza has already explored what ETFs risk during capital flight from emerging markets.
Lula between Washington, Beijing and a conservative Congress
The financial crisis is part of a complex geopolitical framework.
Lula will govern with a predominantly right-oriented Congress, which will be able to limit or modify various economic interventions.
On the international level, Brazil must preserve trade relations with China, the main buyer of its exports, and manage tensions with the United States.
Lula’s victory also represents a discontinuity compared to the recent advance of the Latin American right.
For Italy, the risk concerns, above all, the currency exposure of companies operating on the Brazilian market and financial investments denominated in real. Taxation is also important for investors: from 2026 the rules on the taxation of dividends coming from Brazil have changed.
It does not mean that trade must necessarily decrease. Much will depend on the duration of the devaluation and future economic decisions.
What happens now and what signs to watch for
The first real test for Lula will be the choice of those responsible for economic policy and the definition of the public budget for 2027.
Two decisive steps to understand whether the new government will be able to reconcile social promises with the need to keep debt under control and regain investor confidence.
Brazil has not suddenly become a dead-end economy. It remains a major agricultural, mining and energy power, with a significant domestic market.
Lula’s re-election, however, has brought a decisive question back to the center: who will bear the cost of the balance between social protection, economic growth and debt sustainability?
For families, businesses and investors, the answer will matter much more than the result of a single stock market session.